Navigating Personal Financial Changes After Life Milestones
Major transitions in life often bring about significant shifts in how we manage our daily affairs, household responsibilities, and long-term outlook. Whether it is moving to a new home, starting a career path in a different industry, or simply adjusting to a change in family structure, these moments frequently require a reevaluation of how resources are allocated. Navigating these changes with a clear plan can help create stability, even when the broader environment seems uncertain.
Assessing Your Current Financial Landscape
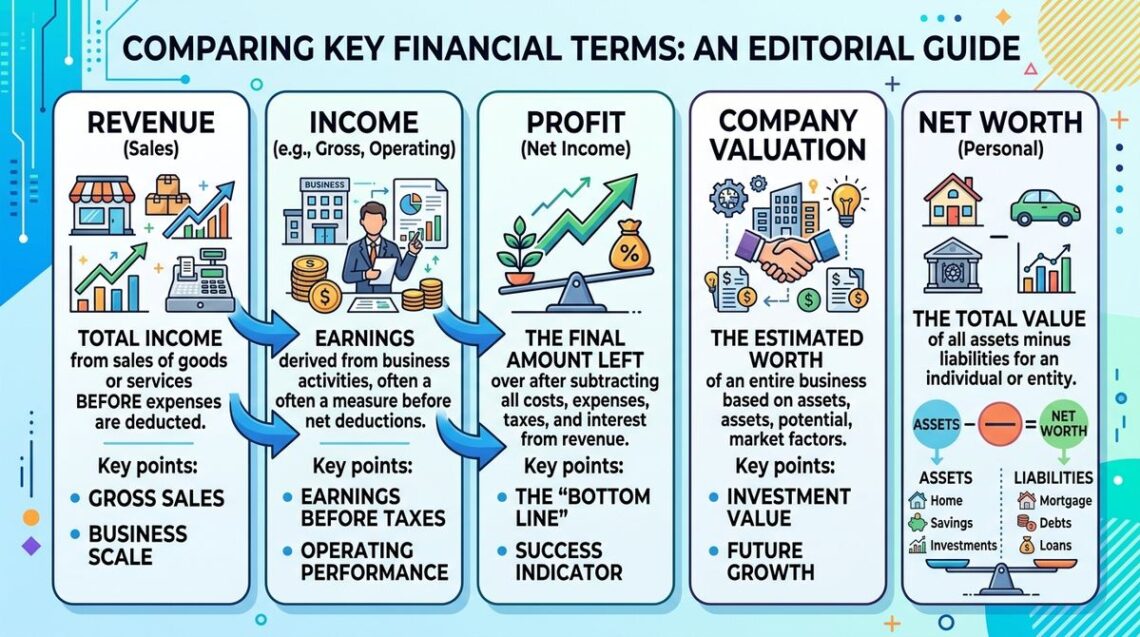
The first step in any transition is often gaining a comprehensive understanding of where you stand. This involves looking beyond just immediate income and expenses to consider how your habits support your broader goals. Many people find that documenting their routine spending for a period helps highlight areas where adjustments might be beneficial, providing a clearer picture of their daily habits.
During times of change, it can be easy to overlook small, recurring commitments that have persisted through previous phases of life. Taking the time to inventory these commitments allows for a more intentional approach to daily management. This reflection is not just about tightening the belt but about ensuring that your resources are being directed in a way that aligns with your current priorities and circumstances.
Evaluating Your Credit Tools for Stability
As you settle into a new routine, the tools you use to manage your day-to-day transactions may need to be assessed. Many individuals find that the strategies they employed in one phase of life are not as effective in another, particularly regarding how they utilize credit. Exploring options for personal loans or understanding how credit products can assist in managing temporary shifts in demand is a common step in this process. You can learn more about how these financial tools are currently utilized by visiting US-creditcards.com to better understand common practices in the modern financial landscape.
It is important to remember that credit is simply a tool, and its effectiveness depends largely on how it is integrated into your broader management strategy. Rather than viewing these tools as a source of additional resources, they are often best understood as mechanisms that, when used carefully, can help bridge gaps or manage cash flow during periods of fluctuation. Approaching them with this perspective can help you avoid common pitfalls and maintain a more stable financial foundation.
Considering Long-Term Investment Potential
While managing daily expenses is a primary concern, looking ahead toward future security is equally important during periods of transition. Understanding the broader market and how different types of opportunities function can be part of a balanced strategy. However, entering this area requires patience and a commitment to learning how markets operate before making any decisions. For those interested in learning more about how investment concepts are perceived, you might find it useful to review the perspectives found at canadian-forex-brokers.com/ as part of your broader research.
It is worth noting that any involvement in market-related activities is generally considered a long-term endeavor. Many find it helpful to focus on education first, understanding the fundamental principles before committing time or effort to any specific approach. Maintaining a focus on learning rather than quick outcomes is often recommended as a way to build confidence and understanding over time.
Creating a Balanced Daily Budget
Once you have a handle on your broader financial tools, turning your attention to the daily budget is the logical next step. A sustainable budget is one that reflects your current lifestyle rather than an idealized version of it. It should be flexible enough to accommodate unexpected events while still providing a clear framework for daily operations. Many people find success by breaking down their budget into simple categories, ensuring that necessities are covered first, followed by allocations for goals and discretionary activities.
Consider the following steps to build your budget:
- Review your actual spending from the previous months to set realistic expectations for your current needs.
- Prioritize essential commitments before considering any discretionary spending.
- Establish a small buffer category to handle minor, unexpected expenses that inevitably arise.
- Revisit your budget plan regularly to ensure it still reflects your evolving situation.
By keeping the process straightforward, you are more likely to stick with it over time. The goal is to build a habit that supports your lifestyle without creating unnecessary stress. Remember that the purpose of a budget is to provide clarity, not to act as a restrictive force that limits your ability to adapt as needed.
Maintaining Focus During Transitions
Ultimately, the way you organize your environment can play a significant role in how effectively you manage your financial and personal transitions. A chaotic space can often lead to a scattered focus, making it more difficult to stay on top of your responsibilities. As you navigate these life changes, finding ways to improve your home workspace can provide the clarity and comfort needed to handle complex tasks, such as budgeting or reviewing your long-term goals. Your physical environment is often the foundation for your mental focus, and taking care of it is a key part of your overall strategy.
Consistency is also vital when adapting to change. It is rarely about making a massive, singular shift that solves everything at once; instead, it is about the steady, incremental improvements you make day by day. By focusing on sustainable practices—whether in how you manage your daily errands, how you utilize financial products, or how you arrange your personal space—you can navigate transitions with greater confidence. Patience is perhaps your greatest asset, allowing you to learn from each stage and move forward in a way that feels intentional and well-considered.


You May Also Like
How to Create a Supportive Community Wellness Network

Managing Tire Wear and Fuel Consumption During a Race
